Swajay91243 views

Hyderabad GCC Boom: 50–70 New Centers in 12 Months

According to a joint report by FICCI and ANAROCK titled 'Hyderabad: The Rise of a Global Capability Powerhouse', Hyderabad is rapidly expanding its footprint as India's premier Global Capability Centre (GCC) destination, outpacing peers like Bengaluru, Pune, and Chennai.


Key takeaways from the report include:


Current Base: 515 GCCs employing over 300,000 professionals (~20% of India's total GCC share).


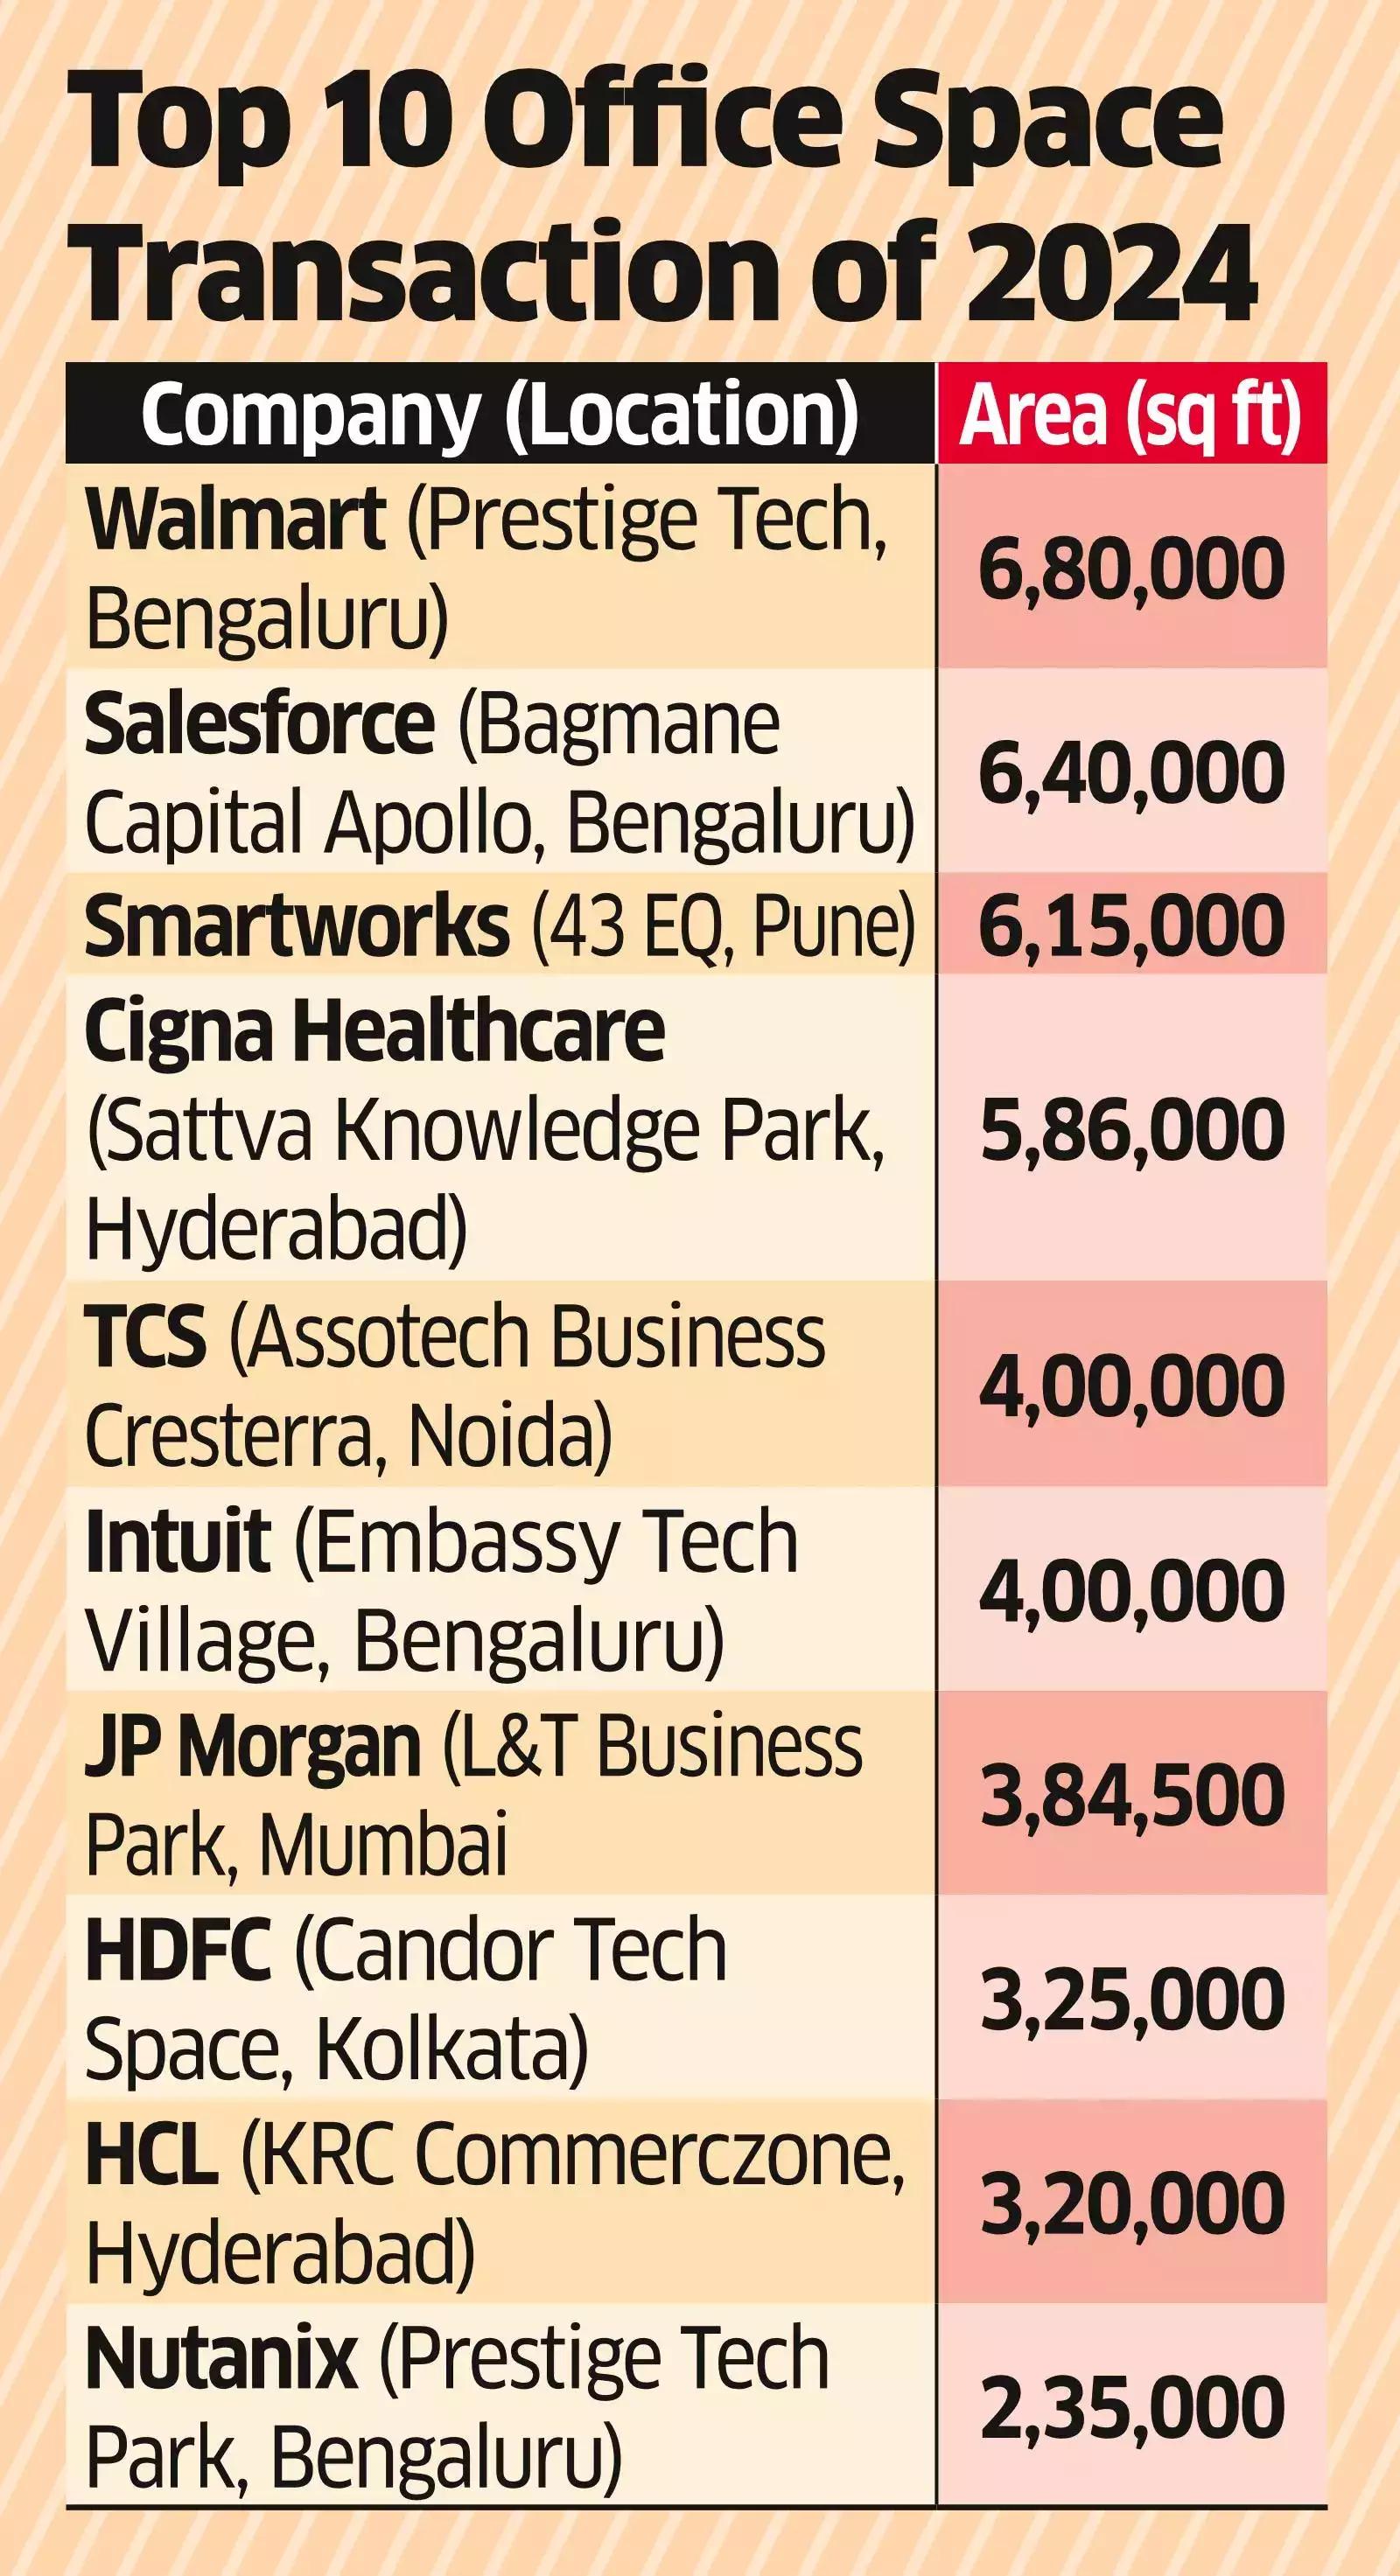
Rapid Leasing Growth: Office space leasing for GCCs surged from 1.9M sq. ft. in 2021 to 4.5M sq. ft. in 2025, with over 3.0M sq. ft. leased in H1 2026 alone.


Cost Efficiency: Grade-A office rentals at ₹95-₹115/sq. ft. offer a major cost advantage over Bengaluru.


Multi-Sector Expansion: Growth is broadening into BFSI, Life Sciences, Semiconductors, Healthcare, and Digital Operations.


Supply Pipeline: With 125M sq. ft. of current Grade-A stock, an additional 36M sq. ft. is entering the pipeline.


With 50 to 70 new GCCs expected to set up within the next year, how do you see this surge impacting commercial real estate yields and residential rental demand across West Hyderabad corridors like Kokapet, Gachibowli, and Financial District?
Discussions

sameer9b4n
From a corporate compliance standpoint, TS-iPASS single-window clearances and state policy incentives are playing a major role in getting GCC fit-outs operational within fast-track timelines.
roja2m7k

@sameer9b4n That streamlined approval timeline is precisely why global enterprises are choosing Hyderabad over delayed infrastructure handovers in other major tech hubs.

sandeep3b6n
3.0M sq. ft. absorption in H1 2026 alone is massive. Most of these GCCs are taking up large footprints in Knowledge City, Nanakramguda, and Neopolis. With institutional developers driving Grade-A supply, commercial yields in Financial District are holding steady around 7.5% to 8.2%.
bhaskar7n3m

@sandeep3b6n Commercial yields look attractive on paper, but for retail investors buying smaller 1,000-2,000 sq. ft. commercial units, lease lock-in terms, fit-out amortization, and vacancy periods need careful tax and cash-flow scrutiny before expecting steady returns.

sandeep3b6n

@sandeep3b6n True, which is why over 80% of these GCCs deal exclusively with institutional Grade-A developers offering single-ownership towers rather than fragmented strata-sold floor plates.

srinath5k1m
I calculated the supply-to-demand matrix: 36M sq. ft. Grade-A supply pipeline vs 3.0M sq. ft. H1 2026 GCC absorption. At ~100 sq. ft. per employee, adding 70 new GCCs equals ~4-5M sq. ft. annual absorption. Commercial vacancy of 23.5% will take 3 to 4 years to absorb completely.
venkatr2n6b

@srinath5k1m Core Grade-A assets in Financial District and Knowledge City actually have sub-10% vacancy. The citywide 23.5% vacancy figure is heavily weighted by peripheral commercial completions along distant ORR stretches.

srinath5k1m

@srinath5k1m Valid point on micro-market segregation. Core FD Grade-A stock will command rental premium growth while legacy Grade-B stock in older hubs like Madhapur or Kondapur will face yield compression.

subbarao1b7n
For residential buy-to-let investors in Kokapet or Nanakramguda, gross rental yields are still hovering around 3.2% to 3.8%. Even with GCC tenant influx, home loan interest rates at 8.5% mean negative cash flow if financed 80% through leverage.
suresh9k4m

@subbarao1b7n Spot on. Residential shouldn't be bought purely for rental yield. The play in Kokapet and Financial District is long-term capital appreciation backed by high-earning GCC tenant occupancy.