meghna7k3m253 views

Kokapet High-Rise Yields: Analyzing Sukhii Ubuntu & Westbrook Returns

Been analyzing Kokapet and Puppalaguda high-rises like I would an equity portfolio. With REITs showing 111% YoY growth and GCCs filling up commercial space near Financial District, the underlying macro demand looks solid. But looking at the ~27-month residential inventory overhang, I’m running IRR models on 3BHK units (around Sukhii Ubuntu and Cybercity Westbrook) to see if the CAGR holds up against current home loan interest rates.


Here are a few quick key metrics I'm crunching:


Pre-EMI vs. Full EMI Cash Outflow:Under-construction units reaching completion by late 2026 offer lower immediate outgo, but holding cost ramps up fast if there's any delay.


Gross Rental Yield Estimate: Expecting ~3.2% to 3.8% based on current 3BHK rents (₹45k–₹65k/mo) against a ~1.6Cr–1.9Cr total entry price.


Capital Appreciation Buffer: Launch prices were around ₹8,800/sq.ft and current asking is near ₹10,800–11,200/sq.ft, so early buyers captured the easy gain. Is there another 12-15% upside post-handover?


Is anyone else modeling entry prices in Kokapet/Puppalaguda right now? How are you guys factoring holding costs versus expected rental yield for 2026-2027 completion projects?

Discussions

sandeep3b6n
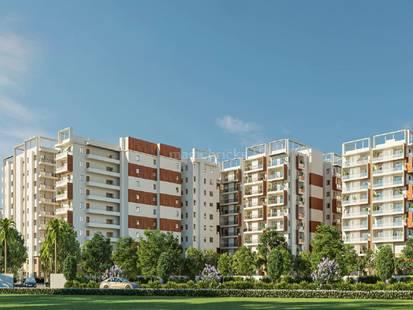
Ground reality comparison between Westbrook and Sukhii Ubuntu: Westbrook's entry ticket around ₹1.2Cr–₹1.5Cr attracts younger IT buyers looking for lower debt, whereas Sukhii Ubuntu's ₹1.65Cr–₹1.95Cr 3BHKs target senior tech managers prioritizing 1,00,000+ sq.ft amenities and LEED Platinum rating.
nikhil7k2m

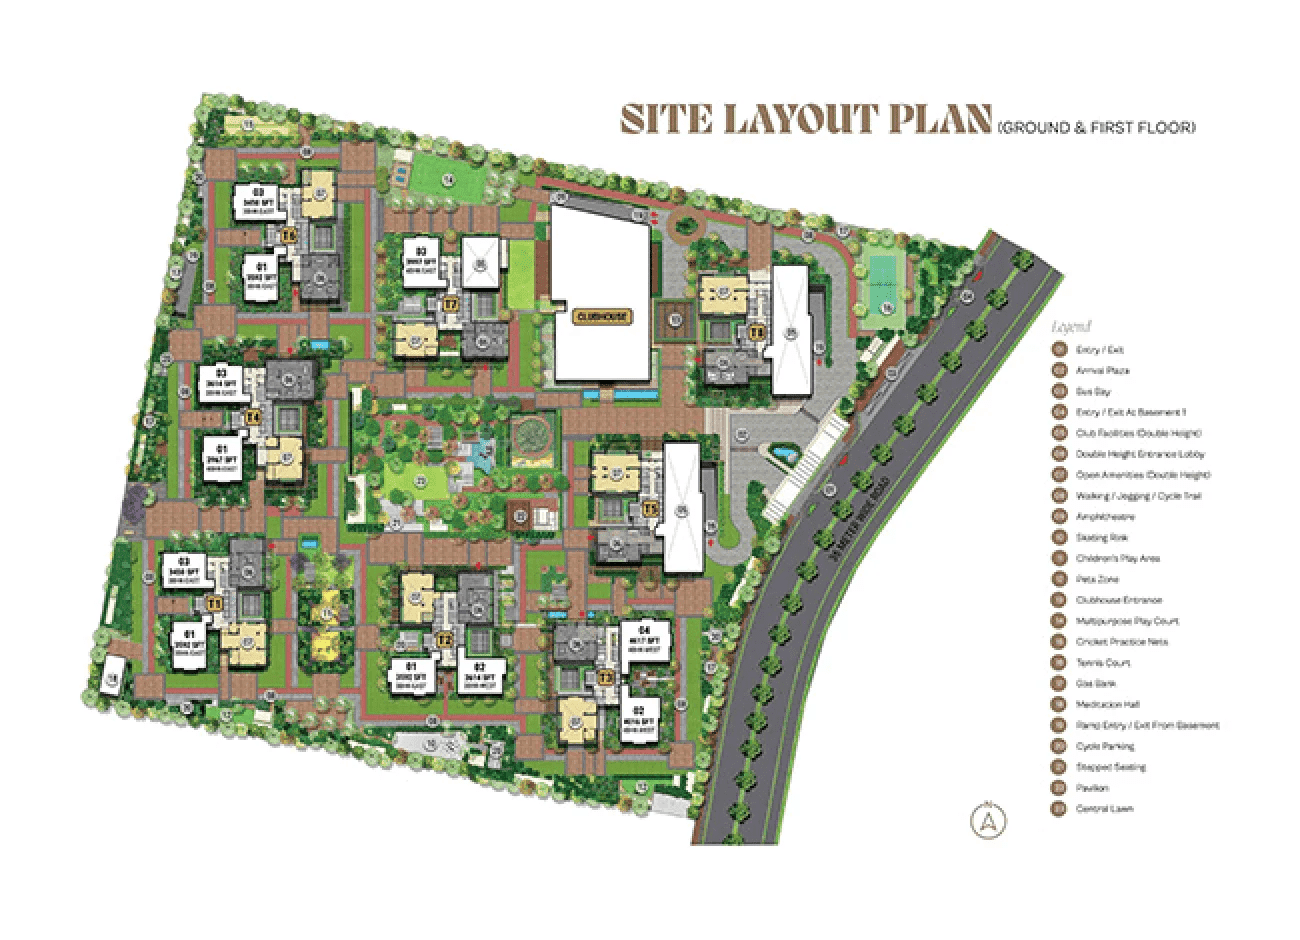
@sandeep3b6n Architectural perspective: Sukhii Ubuntu's all-corner 36-storey tower layout gives great cross-ventilation, but high floor density (855 units on 5.25 acres) means elevator wait times during peak morning hours will depend heavily on high-speed lift specifications.

padma1n6b

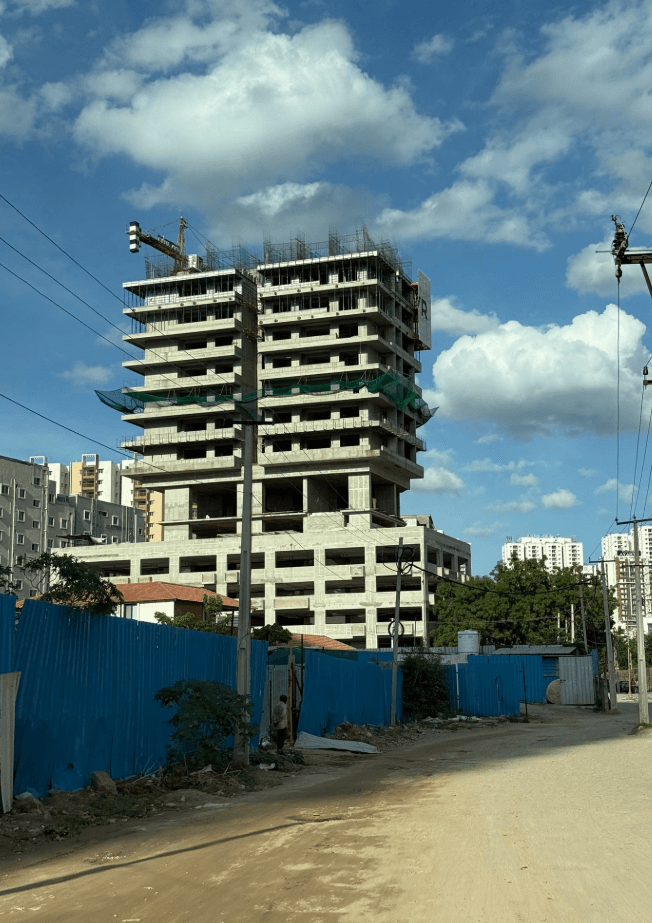
@sandeep3b6n Checked both site progress notes: Ubuntu structural work is ~98% complete heading toward late 2026 handover, so construction execution delay risk is lower now compared to newly launched Neopolis projects.

anusha8k3b
We are comparing 3BHKs in Westbrook vs Ubuntu for self-use and rental backing. Lower pre-EMI outflow during the final 3-6 months of finishing helps our cashflow, but we are keeping a 6-month buffer in case internal finishing slips beyond late 2026.
pavan2n7k

@anusha8k3b Same situation here. Paying rent while waiting for late 2026 handover is manageable only if the builder sticks strictly to the RERA timeline. Double outflow is the biggest fear for end-users.

sureshkd7k3m

@anusha8k3b Running yield comparisons across my spreadsheet: holding for 5+ years post-handover makes cashflows manageable once GCC commercial tenancy matures in the Financial District corridor.

divyanka4k8m
Modeling the net present value on Sukhii Ubuntu and Cybercity Westbrook 3BHKs at ₹10,800/sq.ft: if you assume an 8.5% home loan rate against a 3.5% gross rental yield (₹50k/mo on ₹1.7Cr total outlay), the negative carry is ~₹55k/month post-handover.
subbarao1b7n

@divyanka4k8m Divyanka's math is accurate. Also remember under pre-EMI subvention until late 2026 completion, you only service interest on disbursed tranches, but once physical possession with OC is issued, full principal EMI hits your account.

bhaskar7n3m

@divyanka4k8m Don't forget pre-construction interest set-off limits under Section 24. You can only claim up to ₹2 Lakhs per annum in 5 equal installments post-OC, so the tax shelter doesn't fully offset negative rental carry.

saimurali2b8n
Our price regression analysis across Puppalaguda and Kokapet shows launch-to-handover price expansion from ₹8,800/sq.ft to ₹11,000/sq.ft absorbed most of the early IRR upside. Expecting another 12-15% jump immediately post-handover during a 27-month inventory overhang is mathematically aggressive.
suresh9k4m

@saimurali2b8n Agree on the CAGR compression. For my financial planning clients, I model Kokapet/Puppalaguda high-rises at 6-8% long-term annualized appreciation once handed over, treating it like a stable yield-plus-growth asset rather than a multi-bagger.

nagaraju3k7m

@saimurali2b8n Having held flats through 12 market cycles in Hyderabad, the 12-18 months immediately following handover always see resale price stagnation because flippers dump landlord-share inventory simultaneously.